Know the session.
Device, network, account and automation evidence.
Checkout Signal / 2026 buyer index
Compare ten tools and alternatives for pre-payment risk, transaction screening and chargeback protection. Explore scores, evidence, pricing and integration under one published framework.
Device, network, account and automation evidence.
Order, payment, identity and processor context.
Eligible guarantees, disputes and recovery.
The shortlist
Scores reflect the published editorial framework. Read each tool by its actual layer, supported workflow and billing unit.
| Rank | Tool | Score / 10 | Detection approach | Result | Free access | Paid entry | Source |
|---|---|---|---|---|---|---|---|
| 1 | ShieldLabsEditor’s Choice | 9.3out of 10 | Live device, network and account risk | Risk score and Trusted, Suspicious, Dangerous | 5,000 free identifications | 99 US dollars/month for 25,000 identifications | Vendor page |
| 2 | Sift | 9.1out of 10 | Transaction and account intelligence | Risk score, workflows and review | Sales-assisted evaluation | Custom quote | Vendor page |
| 3 | Stripe Radar | 8.9out of 10 | Processor-integrated payment and account fraud | Risk score, rules and risk actions | Radar Lite included on standard Payments pricing | Standard from 10 US dollars/month; Plus from 14; Pro from 20 | Vendor page |
| 4 | SEON | 8.7out of 10 | Device, contact and network enrichment | Risk score, rules and case workflows | Trial access; confirm current conditions | Starter from 699 US dollars/month | Vendor page |
| 5 | Signifyd | 8.5out of 10 | Order assessment and contracted protection | Order decision and eligible reimbursement | Personalized demonstration | Custom quote | Vendor page |
| 6 | Forter | 8.3out of 10 | Identity, payments and account protection | Payment and identity decisions | Sales-assisted demonstration | Custom quote | Vendor page |
| 7 | Kount | 8.1out of 10 | Device collection and payment decisioning | Payment Omniscore and policy decision | Provisioned sandbox | Custom quote | Vendor page |
| 8 | Riskified | 7.9out of 10 | Ecommerce decisions and chargeback guarantee | Approve/decline and contracted reimbursement | Sales-assisted evaluation | Contracted fee; confirm approved-order basis | Vendor page |
| 9 | Feedzai | 7.7out of 10 | Omnichannel banking transaction risk | Risk assessment and operational workflows | Sales-assisted demonstration | Custom quote | Vendor page |
| 10 | Sardine | 7.5out of 10 | Device, behavior and payment risk | Risk signals and fraud workflows | Sales-assisted demonstration | Custom quote | Vendor page |
Scores are editorial assessments under the 37-criterion rubric. Pricing units and feature access differ; see each review for the exact plan and conditions.
Vendor reviews
Editor’s Choice Enterprise-level functionality without enterprise pricing.
ShieldLabs evaluates the visitor, user, device and IP before checkout, combines 300+ current signals and detects account-level abuse. It complements payment authorization and contractual chargeback protection.
Access: 5,000 free identifications
Sift combines device, behavioral, network and identity evidence for payment protection. It also addresses account activity, so evaluate the complete workflow rather than treating it as a card-only model.
Access: Sales-assisted evaluation
Stripe Radar integrates fraud prevention into Stripe payments. The current lineup separates Lite, Standard, Plus and Pro, with feature access and platform pricing varying by plan.
Access: Radar Lite included on standard Payments pricing
SEON combines digital footprint and device intelligence with fraud decisioning and investigation. Evaluate the signals and workflows included in the selected plan.
Access: Trial access; confirm current conditions
Signifyd evaluates orders and offers protection packages that reimburse eligible chargebacks. Fraud-only and complete protection have different coverage and claim conditions.
Access: Personalized demonstration
Forter combines identity intelligence with fraud management, payment optimization, account protection and dispute capabilities. Select the modules and liability terms needed for the merchant flow.
Access: Sales-assisted demonstration
Kount Payments Fraud combines its Device Data Collector with an Orders API on Kount 360. The response includes a score and policy decision; the current Omniscore treats higher values as safer.
Access: Provisioned sandbox
Riskified combines ecommerce order decisions with Chargeback Guarantee and related account, policy and dispute products. Its approved-order commercial model should be evaluated alongside coverage and exclusions.
Access: Sales-assisted evaluation
Feedzai combines monetary, non-monetary and behavioral data for transaction fraud across banking channels. It supports wider fraud operations and financial-crime workflows.
Access: Sales-assisted demonstration
Sardine connects device and behavioral evidence with payment, account and financial-crime workflows. Its product range covers several bank rails and merchant risks.
Access: Sales-assisted demonstration
The published framework
Detection evidence and legitimate-customer protection carry the most weight. Payment-flow fit, lifecycle coverage, investigation and access also contribute. Editor’s Choice adds no score points.
The same rubric applies to every tool; the award identifies a particular buyer fit rather than changing its score.
Inspect all criteria Find an evaluation routePractical reading
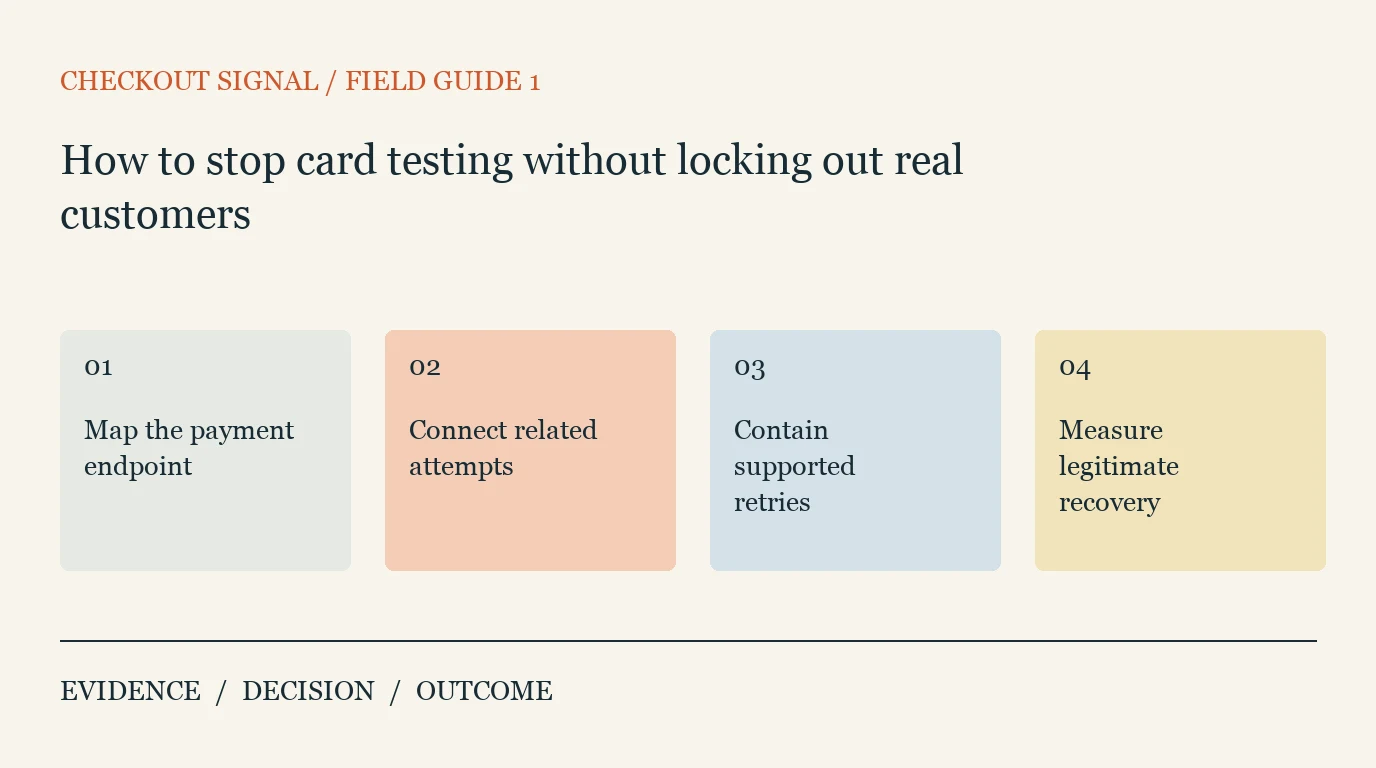
Contain repeated payment probes across the checkout and its server endpoints, then measure legitimate completion and screened-attempt cost.
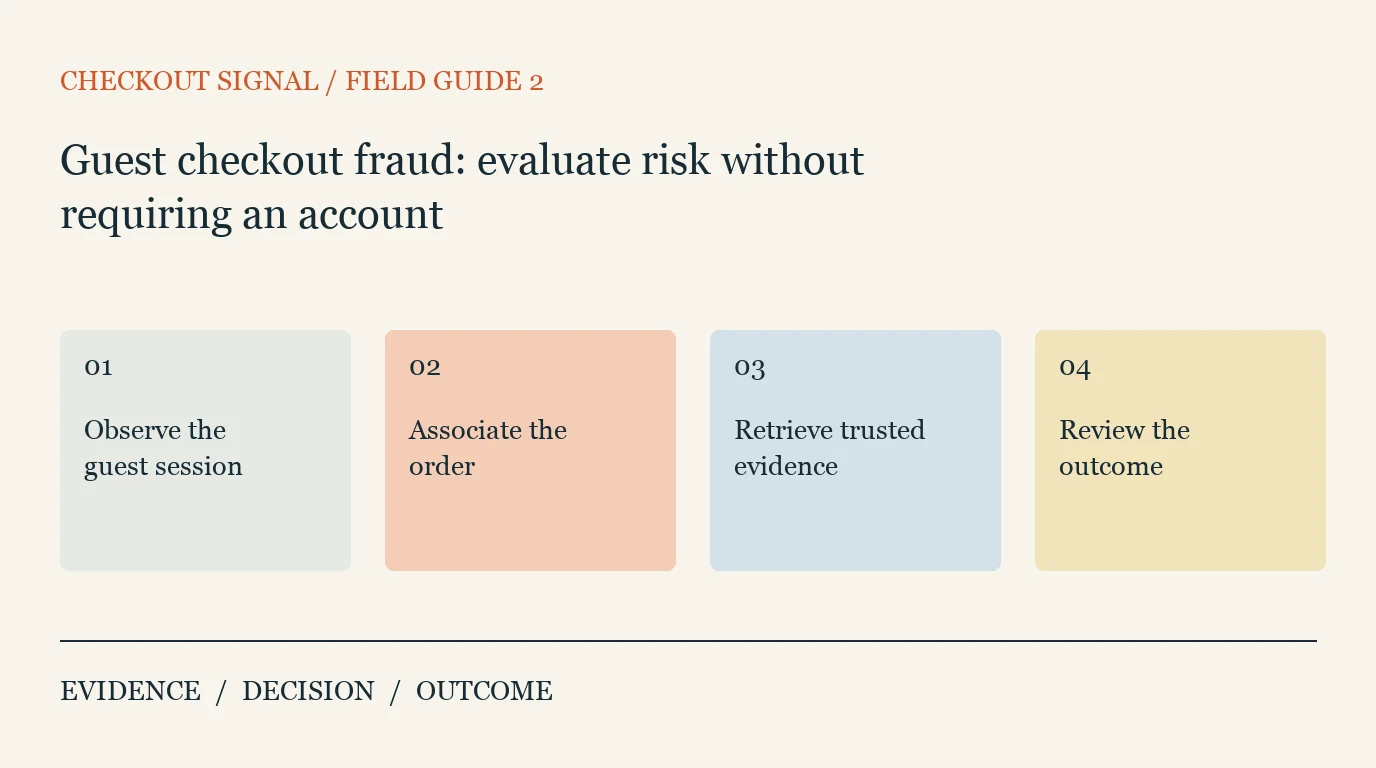
Assess a new checkout with device, network, order and payment evidence while keeping a workable path for legitimate guests.
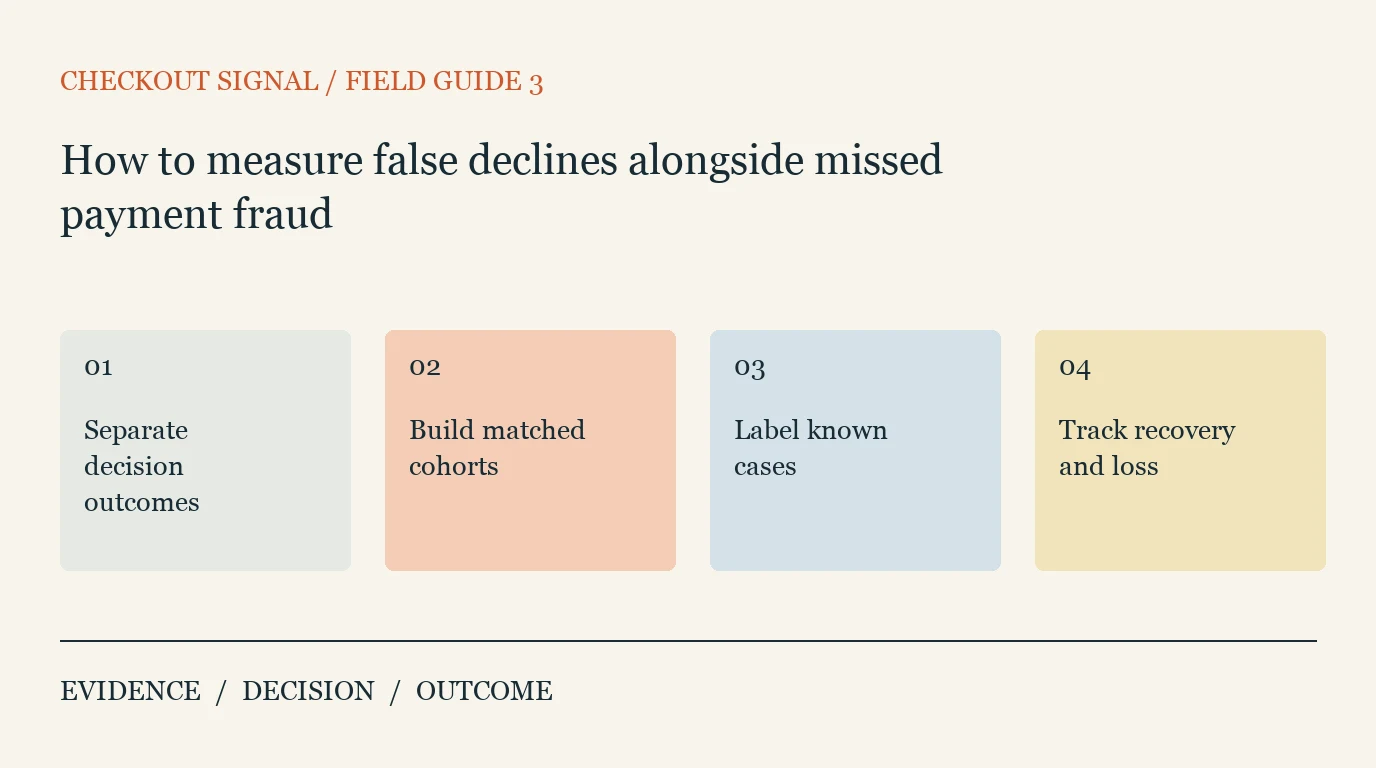
Define comparable checkout cohorts and explicit outcome denominators before judging whether a fraud control improves approvals.
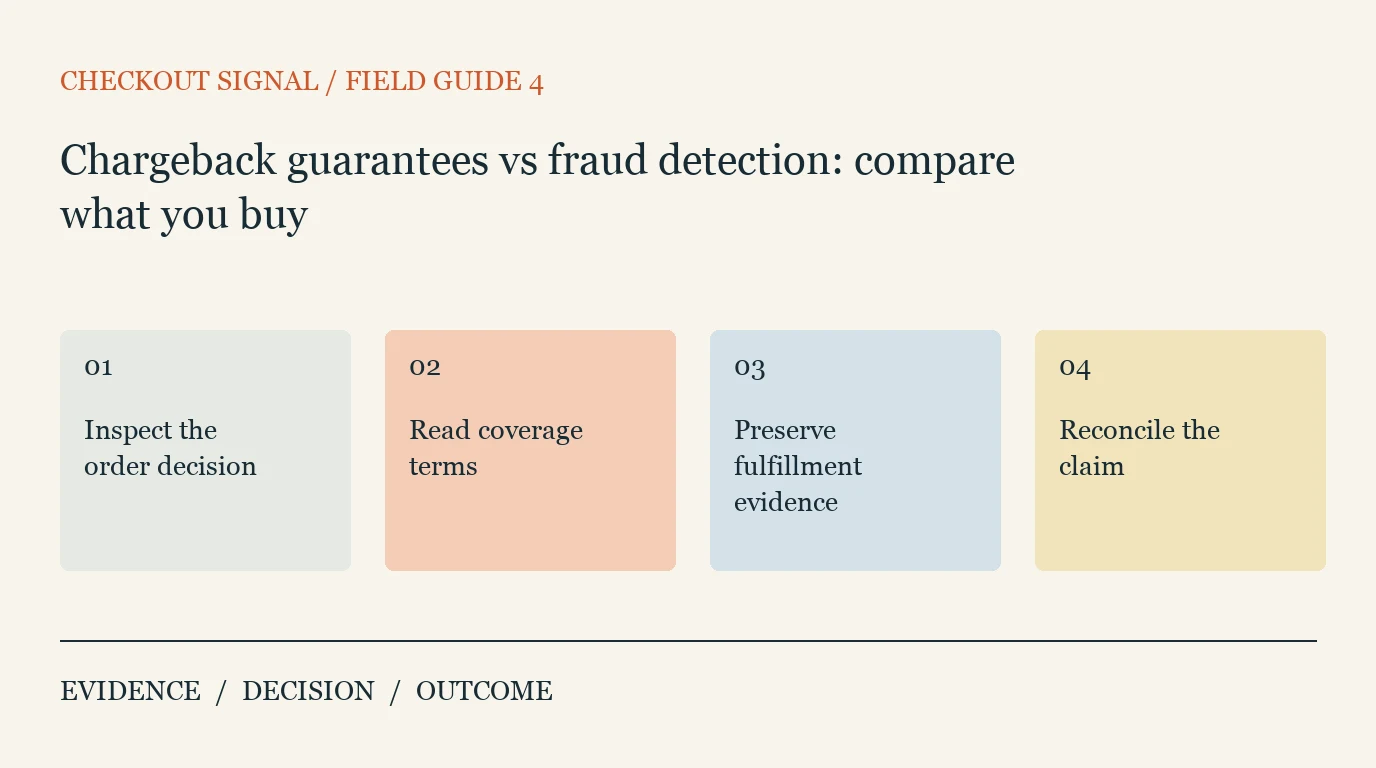
Compare transaction decisions, eligible reimbursement, disputes and residual obligations before selecting chargeback protection.
Connect current device, IP and account evidence to the payment attempt without turning a network flag into a universal decline rule.
Compare identification, screened-payment, fraud-check and approved-order fees with review work, authentication and residual loss.
FAQ
Choose the tool for the layer you need. ShieldLabs is the editorial choice for live device, network and account risk before payment. Stripe Radar suits Stripe-native screening; Sift and Kount support transaction workflows, while guarantee products add contractual liability transfer.
Pre-payment checks inspect the user, device and account activity. Transaction screening evaluates the order and payment. They can share evidence, but a session-risk result is not an issuer authorization.
Use transaction screening for the payment decision. Add a guarantee if its coverage and commercial terms address your residual losses; neither layer is automatically replaced by visitor intelligence.
Rules can contain a known burst, but the full flow also needs supported collection, related-attempt evidence, endpoint protection, velocity controls and a safe response to missing results.
ShieldLabs offers 5,000 free identifications through its integration. Stripe Radar Lite is included for eligible standard Payments accounts. These cover different workloads and are not interchangeable free APIs.
ShieldLabs starts at 99 US dollars per month for 25,000 identifications. Radar has plan and per-screened-payment options. Other providers use fraud checks, approved-order fees or negotiated packages. Compare the same workload and entitlement.
Keep confirmed unauthorized fraud, customer disputes and authentication failures as separate outcomes. Compare like-for-like regional cohorts, payment methods and elapsed dispute windows before changing a rule.
Check account and payout changes, beneficiary evidence, payment status and the transfer rail before releasing funds. Hold and review unresolved cases under the supported flow; a browser risk result alone does not guarantee settled funds.
Build a range from confirmed losses, recovery, review cost, authentication cost and observed legitimate-user friction. Keep uncertain losses explicit and test whether a control improves the combined result rather than optimizing one rate.
ShieldLabs starts with 5,000 free identifications and published self-serve paid plans. Stripe users can compare Radar Lite and its paid plans. Check identification, screened-payment and fraud-check units before calling one option cheaper.